When a Paper Mill Stops Guessing About Demand
AI is rewiring procurement, scheduling and logistics in the pulp and paper industry — and it offers lessons for supply managers in any process industry.
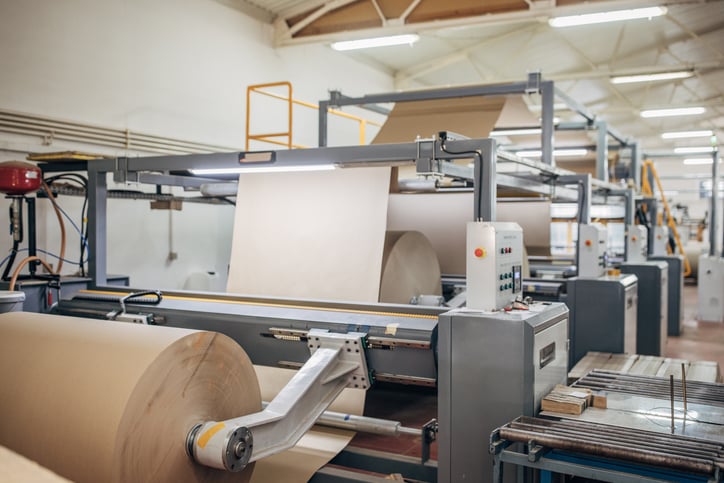
A paper mill is an unforgiving place to be wrong about demand. Raw material comes from standing timber and recovered-fiber markets that move with weather, freight rates and scrap prices. Production runs continuously, and stopping a machine to change grades costs money by the minute.
For decades, supply managers absorbed that volatility with inventory and experience. Both are getting more expensive.
Post-coronavirus pandemic demand swings, tighter fiber availability and Scope 3 reporting under the European Union’s (EU) Corporate Sustainability Reporting Directive have made buffer-and-react planning look less like prudence and more like cost. AI is changing the calculation — not as one system dropped into the plant, but as a layered set of models attacking a different problem at each echelon.
Two publicly documented programs, at WestRock and Kimberly-Clark Corporation, show what that looks like and where the hard parts are.
Three Echelons, Three Problems
Separating the supply chain into three layers — upstream, midstream and downstream — makes more sense than considering AI as a single capability, because the data, the decision speed and the failure modes differ in each.
Upstream is fiber procurement, where the problem is quality variability and price risk. Mills now pair near-infrared spectroscopy with computer vision models that inspect recovered paper bales on the conveyor, flagging plastics, metals and contaminants before material reaches the pulper.
This results in accuracy of about 95 percent, research shows, compared to roughly 78 percent for human inspectors on a full shift — and every bale gets inspected rather than a fraction of a percent.
Machine learning time-series models have also cut 30-day price forecast error on recovered paper indexes to about 6 percent, against roughly 15 percent for conventional benchmarks — the difference between buying into a trough and buying at spot all year.
Midstream is mill scheduling, which is dominated by trim loss — waste created when master rolls are cut to customer widths. Classical optimization creates an effective plan for 24 to 72 hours, but can take an hour to resolve, which is useless when a machine goes down mid-shift.
What works better is a hybrid: Mathematical optimization builds the baseline schedule, and a reinforcement (AI) learning agent handles exceptions in seconds. This results in about 11 percent less trim waste and disruption recovery falling from about 47 minutes to under 90 seconds, research shows.
Downstream is demand and distribution. Because statistical forecasting extrapolates from shipment history, it cannot see a signal that has not yet become a shipment — which is why tissue demand spikes of several hundred percent within 72 hours in early 2020 were invisible until shelves were empty.
Demand-sensing platforms instead ingest retail point-of-sale data, promotions and regional variables; in consumer tissue, weekly influenza surveillance leads demand by two to three weeks. Comparative research reports roughly a third less forecast error at the SKU-distribution center level and about 22 percent lower safety stock.
Two Programs, Two Scenarios
At WestRock, where hundreds of converting plants source paperboard from dozens of mills and where excess inventory carries cost and a stockout stops a line, coordination was an issue.
The company built a digital twin of its network, fed by models generating probabilistic forecasts at the SKU-mill level on a rolling 13-week horizon. Its 2025 supply chain resiliency report attributed a roughly 18 percent reduction in mill-finished goods inventory to the program, with service levels held above 97 percent and about 12 percent lower per-metric-ton transportation cost from AI freight consolidation.
Kimberly-Clark’s problem was volatility at the consumer interface. Its demand-sensing platform replaced a monthly forecast cycle with daily SKU-distribution center signals. The company reported roughly 28 percent lower forecast error at the four-week horizon and about 19 percent less system-wide safety stock without loss of on-shelf availability.
Those signals feed mill scheduling directly, breaking the bullwhip effect: Real sell-through replaces lagged shipment data as the production trigger.
What the Two Cases Agree On
While the two companies’ implementations diverge, three points converge — and those are the transferable ones.
In both cases:
- AI is deployed as a layered stack across planning horizons rather than one system
- Years of data infrastructure work occurred beforehand; neither would run without sensor coverage, a unified data environment and partner integration.
- Infrastructure is a prerequisite, not a parallel workstream — industry estimates put it at 60 to 70 percent of total program cost in legacy manufacturing.
- Humans are kept in the loop, which is not timidity but an accurate read of where these models are weakest: novel, low-data disruptions.
Barriers Nobody Budgets For
Fragmented data gets the attention. The under-budgeted barrier is operator trust.
With mill schedulers, tacit knowledge — how a machine behaves on a specific grade, which carrier actually shows up — is genuinely absent from historical data. When a model recommends something counterintuitive, it is overridden — and the optimization value evaporates quietly.
Explainability addresses this directly: Manufacturing scheduling research has found operator acceptance rising from 52 percent to 81 percent when explanations accompanied recommendations, with no measurable loss in solution quality.
Built in from the start, it costs a fraction of retrofitting it after a deployment has lost the confidence of the people running the plant. Pair it with a feedback loop that captures overrides and uses them to retrain. An override is information, not insubordination.
Where Profitability and Emissions Stop Competing
The most consequential point for supply management is that in this sector the efficiency case and the sustainability case are largely the same case.
Less trim waste means less virgin fiber and process water per ton. Better load density means fewer trucks. Lower safety stock means fewer emergency freight moves — both the most expensive and the most carbon-intensive shipments a network makes.
That changes how the business case is written. AI investment here does not need to be argued as sustainability spending justified on soft benefits; it is an efficiency program whose emissions reduction is a mechanical consequence of the same optimization.
One caution: The figures above are company-disclosed and generally not independently audited. Treat them as directional evidence of what is achievable, not as benchmarks to hold a supplier to.
Where to Start
For mills and plants at an earlier stage of digital maturity, the deployment logic is replicable and roughly sequential:
- Consolidate the data layer first — sensor coverage, a unified data environment and partner integration
- Deploy point-solution models where the economics are clearest and the data is already good: price forecasting, quality inspection or freight consolidation
- Build explainability and override capture into the first deployment, not the third.
- Connect the point solutions across planning horizons only after individual models have earned operator trust
- Establish decision accountability and audit trails before granting any model autonomous authority over spend.
As Scope 3 accountability and circular economy obligations tighten, running a supply chain that is simultaneously cheaper and lower-emitting shifts from competitive advantage to condition of entry.
That capability takes years to build. It is the real argument for starting now — not the technology, which will keep changing, but the runway.
(Photo credit: Getty Images/South Agency)